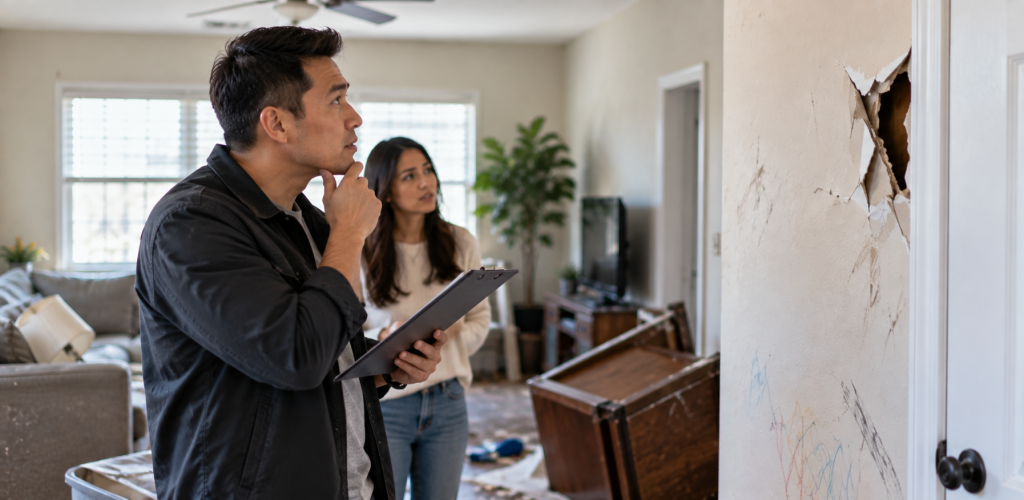
Tenant-caused damage is one of the more confusing areas of landlord insurance — what's covered, what falls to the security deposit, and what requires pursuing the tenant directly aren't always clear. Understanding how these pieces fit together in advance can save real frustration when damage actually happens.
Table of Contents
1. What Landlord Insurance Typically Covers
2. The Role of the Security Deposit
3. Malicious Damage vs. Normal Wear and Tear
4. How Trust Partners Insurance Can Help
1. What Landlord Insurance Typically Covers
🔥 Sudden and Accidental Damage
A landlord policy generally responds to sudden, accidental damage — a tenant accidentally starting a kitchen fire, a burst pipe from something a tenant did unintentionally, or similar unplanned events, even if a tenant's actions were involved.
🎭 Vandalism and Malicious Mischief
Deliberate destruction — holes punched in walls out of anger, intentional damage during a contentious move-out — is often covered under a vandalism or malicious mischief endorsement, though this is worth confirming specifically, since not every policy includes it by default.
📉 What Standard Policies Generally Exclude
Gradual damage from neglect — mold from unreported leaks, pest infestations from poor upkeep, or general deterioration from a tenant simply not maintaining the space — typically falls outside standard coverage, since insurance is built for sudden loss, not ongoing neglect.
2. The Role of the Security Deposit
💵 Your First Line of Defense
For most modest tenant-caused damage, the security deposit is the appropriate first resource — it's faster, doesn't involve a claim or a deductible, and doesn't risk affecting your loss history with the carrier.
📸 Documentation Matters on Both Ends
Thorough move-in and move-out photo documentation protects you if a deposit dispute arises, and also serves as useful evidence if damage is significant enough to require an insurance claim in addition to the deposit.
⚖️ Texas Security Deposit Rules Apply
Texas law sets specific requirements around returning security deposits and itemizing deductions within a defined timeframe. Following these rules carefully protects you if a dispute over damage-related deductions ever escalates.
3. Malicious Damage vs. Normal Wear and Tear
🧭 Knowing the Difference Matters
Faded paint, minor carpet wear, and small nail holes from hanging pictures are considered normal wear and tear — not something you can charge against a deposit or claim on insurance. Broken fixtures, large holes, or stained carpet from neglect fall into a different category entirely.
📝 Set Clear Expectations in the Lease
A lease that clearly defines what's considered tenant responsibility versus normal wear and tear reduces disputes significantly, and gives you a clear reference point if a disagreement over damage does arise.
💼 When It's Worth Pursuing a Former Tenant Directly
For damage that significantly exceeds the security deposit and doesn't clearly fall under an insurance claim, pursuing the former tenant directly — sometimes through small claims court — may be a more appropriate path than filing with your carrier.
4. How Trust Partners Insurance Can Help
🤝 We Help You Understand What's Actually Covered
Trust Partners Insurance helps DFW landlords understand exactly what their policy responds to when tenant-caused damage occurs, so you know whether to use the deposit, file a claim, or both.
📞 Dealing With Tenant Damage? Call Us
If you're facing significant tenant-caused damage and aren't sure how to proceed, reach out to our team. We'll help you understand your coverage and the right next step.